Nigeria Introduces Fresh Stablecoin Licenses and Capital Mandates
Nigeria's central bank introduced a fresh framework governing non-security virtual assets, establishing dedicated stablecoin licenses with specific capital mandates, reserve standards, and local presence rules.

TL;DR: On November 5, Nigeria’s central bank introduced a fresh framework governing non-security virtual assets, establishing dedicated stablecoin licenses separated by naira and foreign-currency tokens. These guidelines mandate specific capital, reserve, and local presence standards while prohibiting particular algorithmic models. Fundamentally, this addresses payment regulation rather than offering universal legalization for all cryptocurrency operations.
Nigeria is transitioning away from general digital asset policy discussions and implementing comprehensive guidelines for the companies that issue and transfer them. Through a November 5 circular and its related regulations, the Central Bank of Nigeria established a licensing structure that encompasses stablecoins, payment processing, custody solutions, transfers, and remittances for non-security virtual assets.
Because international stablecoin providers cannot assume that foreign issuance or an external smart contract exempts them from Nigerian jurisdiction, this framework carries significance well outside the country’s borders.
Two stablecoin classes, with different obligations
The central bank separates stablecoins into two categories based on their reference assets: Class 1 involves naira-linked issuers, whereas Class 2 handles tokens backed by foreign currencies. Published reports on these regulations emphasize the minimum paid-up capital thresholds of 10 billion naira for Class 1 and 15 billion naira for Class 2, with the central bank maintaining the authority to demand higher sums.
Every token must secure individual approval. The regulator mandates detailed disclosures concerning reserves, redemption procedures, compatible blockchain networks, governance structures, and risk management. This process demands considerably more effort than simply deploying a dollar-peaked smart contract and launching a branded website.
These regulations prioritize backing and redemption integrity, placing bans on algorithmic systems that depend primarily on market forces instead of qualifying reserve assets to uphold their value. Consequently, users must evaluate not only if a token maintains its peg, but also whether the issuer possesses the capacity to fulfill redemptions and protect funds during periods of market stress.
Cross-border operators cannot ignore local rules
The circular dictates that the framework governs activities carried out within or originating from Nigeria, aimed at Nigerian residents, or having a substantial impact on the nation’s financial and payment networks. Lacking a physical office does not automatically grant immunity. Therefore, global stablecoin platforms might need to address local incorporation and licensing requirements prior to actively engaging the local market.
Furthermore, the central bank separates its oversight of payments and non-security assets from the duties handled by Nigeria’s securities regulator. Digital products with investment characteristics can prompt separate regulatory scrutiny, meaning the precise legal definition of an asset takes precedence over general marketing terminology like “crypto.”
This regulatory division mirrors findings from NewsBTC regarding Coinbase limiting specific stablecoins within the EEA. Both scenarios demonstrate that while a token may remain active on a ledger, the authority of platforms to provide it to consumers varies by region.
A compliance test for issuers and payments firms
The Nigerian guidelines enforce strict anti-money-laundering protocols, sanctions screening, transaction surveillance, asset safeguarding, and customer disclosures. While these responsibilities can present heavy financial burdens for smaller businesses, the regulator explicitly emphasizes consumer safety and the stability of the financial system alongside technological progress.
Transitional arrangements are available for current market participants; organizations should consult the official regulatory text directly to determine individual deadlines and authorization mandates rather than relying on news reports for legal guidance. Speculating on the exact quantity of approved licenses remains premature.
For everyday users, the primary measure of success will be whether compliant products deliver reliable redemption processes, clear fee structures, and dependable cross-border payment utility. For issuers, the key challenge lies in satisfying strict reserve and governance mandates while preserving viable economics. Although Nigeria has established a much more defined regulatory structure, the ultimate market reaction depends on actual compliant deployments.
This article was written by the News Desk and edited by Samuel Rae.
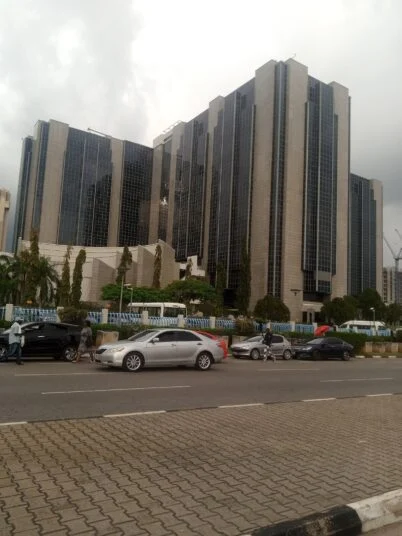
Featured image: Central Bank of Nigeria headquarters in Abuja (2023 illustrative photograph of the CBN building). Photo: Umabruka via Wikimedia Commons, licensed under CC BY-SA 4.0.
Short FAQs
When did the Central Bank of Nigeria issue the new framework?
The Central Bank of Nigeria issued the new framework and circular on November 5.
What are the minimum capital requirements for stablecoin issuers?
The minimum paid-up capital requirements are 10 billion naira for Class 1 (naira-referenced) issuers and 15 billion naira for Class 2 (foreign-currency-backed) issuers, though the central bank retains the power to prescribe higher amounts.
Are algorithmic stablecoins allowed under the new rules?
The rules restrict algorithmic arrangements that rely primarily on market mechanisms rather than eligible reserve assets to maintain their value.
Does the framework apply to international stablecoin businesses?
Yes, the framework applies to regulated activities conducted in or from Nigeria, directed at Nigerian residents, or materially affecting Nigerian payment and financial systems, meaning a physical absence does not automatically exempt an international platform.